


An Arizona used car dealer choosing between garage liability vs dealers open lot insurance is really choosing between two different layers of protection: one covers your operations broadly, the other covers vehicles sitting on the lot. Most dealers eventually need both pieces of auto dealer insurance to stay properly covered and licensed.
Garage Liability vs Dealers Open Lot Insurance: The Coverage Difference Explained
Garage liability insurance and dealers open lot insurance are not the same coverage, even though they're often sold together in the same auto dealer program. Garage liability is a liability policy: it responds when your dealership causes bodily injury or property damage to someone else, whether that happens in your showroom, during a test drive, or while a vehicle is in your care for service. Dealers open lot insurance, sometimes called open lot insurance, is a physical damage coverage instead. It protects the vehicles in your own inventory from fire, theft, vandalism, hail, and other named perils while they sit on your dealer open lot.
In practical terms, garage liability protects other people and their property from your dealership, while dealers open lot protects your own inventory from loss. Confusing the two, or assuming one substitutes for the other, is one of the most common coverage gaps on an Arizona used car dealer's policy.
What Garage Liability and Dealers Open Lot Each Actually Cover
What Garage Liability Insurance Covers for an Arizona Used Car Dealer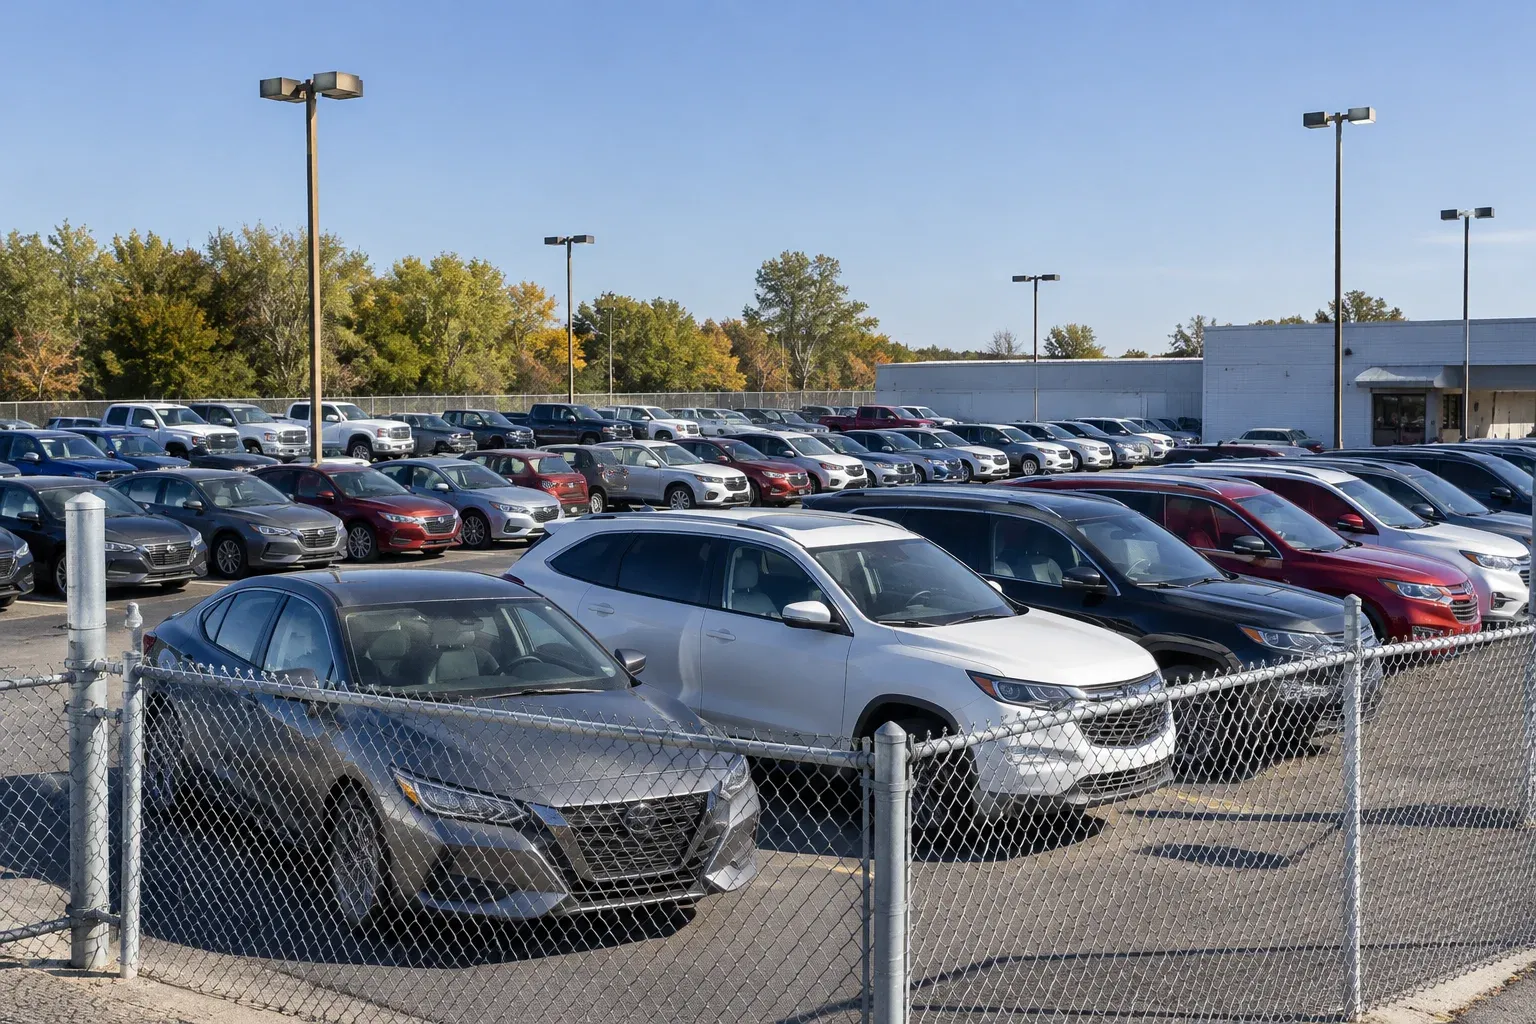
Garage liability insurance combines general liability coverage with garagekeepers legal liability built for dealership operations. The general liability portion works much like the general liability coverage most businesses carry: a customer slip-and-fall in your showroom, a sign that falls on a passerby, or an advertising injury claim. The garagekeepers piece is what makes it dealer-specific: it covers your legal liability for the care, custody, and control of a customer's vehicle while it's in your possession, for example if an employee damages a trade-in while moving it around the lot.
Garage liability also generally extends to test drives. When a customer or salesperson test drives a vehicle from your inventory and causes an accident, garage liability is typically the coverage that responds to injuries or property damage from that test drive, along with vehicles being transported between your dealer open lot and another location. Because what counts as "in transit" or "on a test drive" varies by carrier, it's worth confirming the exact wording with your agent rather than assuming.
What Dealers Open Lot Insurance Covers
Dealers open lot insurance is narrower and more specific. It's a physical damage form that covers the used vehicles in your own inventory against loss from fire, theft, vandalism, windstorm, hail, and similar perils while they're parked on your lot. It does not cover liability for injuries, it does not cover a customer's accident during a test drive, and it does not cover damage your dealership causes to someone else's property. If a windstorm damages several vehicles on your dealers open lot overnight, that open lot insurance is what pays for the loss, not garage liability.
Arizona Licensing Rules and Whether You Need Both Coverages
Getting Licensed as a Used Car Dealer in Arizona
Arizona requires used car dealers to hold a dealer license through the Arizona Department of Transportation Motor Vehicle Division, and that process generally calls for proof of liability insurance at set minimum limits along with a dealer bond. Because open lot coverage is a physical damage form rather than a liability policy, it typically cannot satisfy that liability insurance requirement on its own. In most cases, an Arizona used car dealer needs garage liability insurance in place to meet licensing, with dealers open lot coverage added on top to protect the inventory itself. If you're unsure whether your current policy actually satisfies your license renewal, that's worth confirming directly with your agent before your renewal date rather than after.
Does a Used Car Dealer Need Both Coverages?
For most Arizona used car dealers, yes. A small independent used auto lot that only buys and resells vehicles, without a service bay or regular test drives, still needs garage liability to meet licensing and to cover basic liability exposures, and benefits from dealers open lot coverage any time the value of parked inventory is meaningful. A larger car dealership running test drives daily, offering financing, or doing light mechanical work carries more liability exposure and typically needs a fuller garage liability program alongside open lot coverage. The right mix comes down to how much inventory sits exposed on the lot, how much customer and vehicle interaction happens day to day, and what your license requires: exactly the kind of comparison an agent can walk through against your actual operations.
What Drives the Cost of Garage Liability Coverage
Garage liability pricing for an Arizona used car dealer depends on factors like the number of vehicles sold each year, how many employees you carry (including whether you also need Arizona workers compensation insurance), whether test drives and light service work are part of daily operations, your claims history, and the liability limits your license and lender require. Dealers open lot pricing is driven more by the total value of inventory typically parked on the lot at any given time and the location's exposure to theft or weather. Because every dealership's mix of vehicles, employees, and operations is different, the only way to get an accurate number is a quote built around your actual lot rather than an industry average. An Arizona used car dealer weighing garage liability vs dealers open lot limits ahead of a license renewal can get an insurance quote that lines both coverages up side by side before deciding.
Closing the Coverage Gap Between Open Lot and Garage Liability
When a Claim Falls Through the Gap
The costliest mistake an Arizona used car dealer can make is assuming dealers open lot coverage will respond to a liability claim. If a customer test drives a car from your lot and causes an accident, or a mechanic damages a customer's vehicle while it's in your care, an open-lot-only policy typically will not pay that claim, because open lot coverage was never written to cover liability in the first place. The dealer is left personally exposed for injuries, property damage, or a lawsuit that a properly structured garage liability policy would have covered.
How to Switch from Open Lot to Full Garage Liability Coverage
Moving from a bare dealers open lot policy to a full garage liability program usually starts with a review of your actual operations: vehicle count, employee count, whether test drives happen daily, and what your license requires. From there, an agent can quote a combined program that layers garage liability and physical damage protection for your inventory into one package, timed to replace the old policy without a lapse in coverage. Coordinating the effective dates matters, since a gap between canceling the old policy and binding the new one leaves the dealership uninsured in the meantime.
Frequently Asked Questions
Is dealers open lot insurance the same as garage liability insurance? No. Dealers open lot insurance is a physical damage coverage that protects the vehicles in your own inventory from fire, theft, vandalism, and weather while they're parked on the lot. Garage liability insurance is a liability policy that responds when your dealership causes injury or property damage to someone else. Most Arizona used car dealers need both, not one instead of the other.
Does garage liability cover test drives? Garage liability insurance generally extends to vehicles being test driven by a customer or salesperson, covering injuries or property damage caused during that drive. Dealers open lot coverage does not respond to test drive accidents, since it only covers physical damage to your own inventory. Confirm the exact test drive wording in your policy with your agent, since carrier language can vary.
Can I start with dealers open lot coverage and add garage liability later? Some dealers start with open lot coverage to protect inventory value, but Arizona licensing generally requires proof of liability insurance, which open lot coverage does not provide on its own. Most dealers need garage liability in place from day one to get licensed, then adjust open lot limits as inventory value grows.
What's the minimum liability insurance an Arizona auto dealer must carry? Minimum liability limits for a dealer license are set by the Arizona Department of Transportation Motor Vehicle Division and can change, so the current requirement should be confirmed directly with MVD or a licensed agent before you buy a policy. Carrying limits below what your license and lender require can hold up a renewal.
Get Your Garage Liability and Dealers Open Lot Coverage Reviewed
An Arizona used car dealer running mismatched or bare-minimum coverage is one claim away from a gap that costs far more than the premium difference would have. Insurance All Stars can review your current program and quote dealers open lot coverage alongside full garage liability so your dealership and your inventory are both actually protected.